The Thailand Retirement Dream Has Fine Print: 6 Things to Check First
The food, costs, and warm weather are real. So are the details people skip while they are still in love with the idea.
We may earn a commission when you book or buy through links in this article.
A retirement plan can contain excellent noodles and still need work. The trick is to enjoy the good parts while asking the questions that do not fit under a beach photograph: where will you live, how will you get around, and what happens when you need help?
1. A vacation is not a long-stay plan
A holiday can show you a destination. It does not prove that your chosen long-stay route fits your income, age, nationality, paperwork, or renewal needs. Treat the current official rules as a starting point, not a memory from a blog post.
Try this: Keep a dated document checklist and ask about renewal requirements as well as the initial application. A plan for arrival is only the first page.
2. Thailand is not one retirement experience
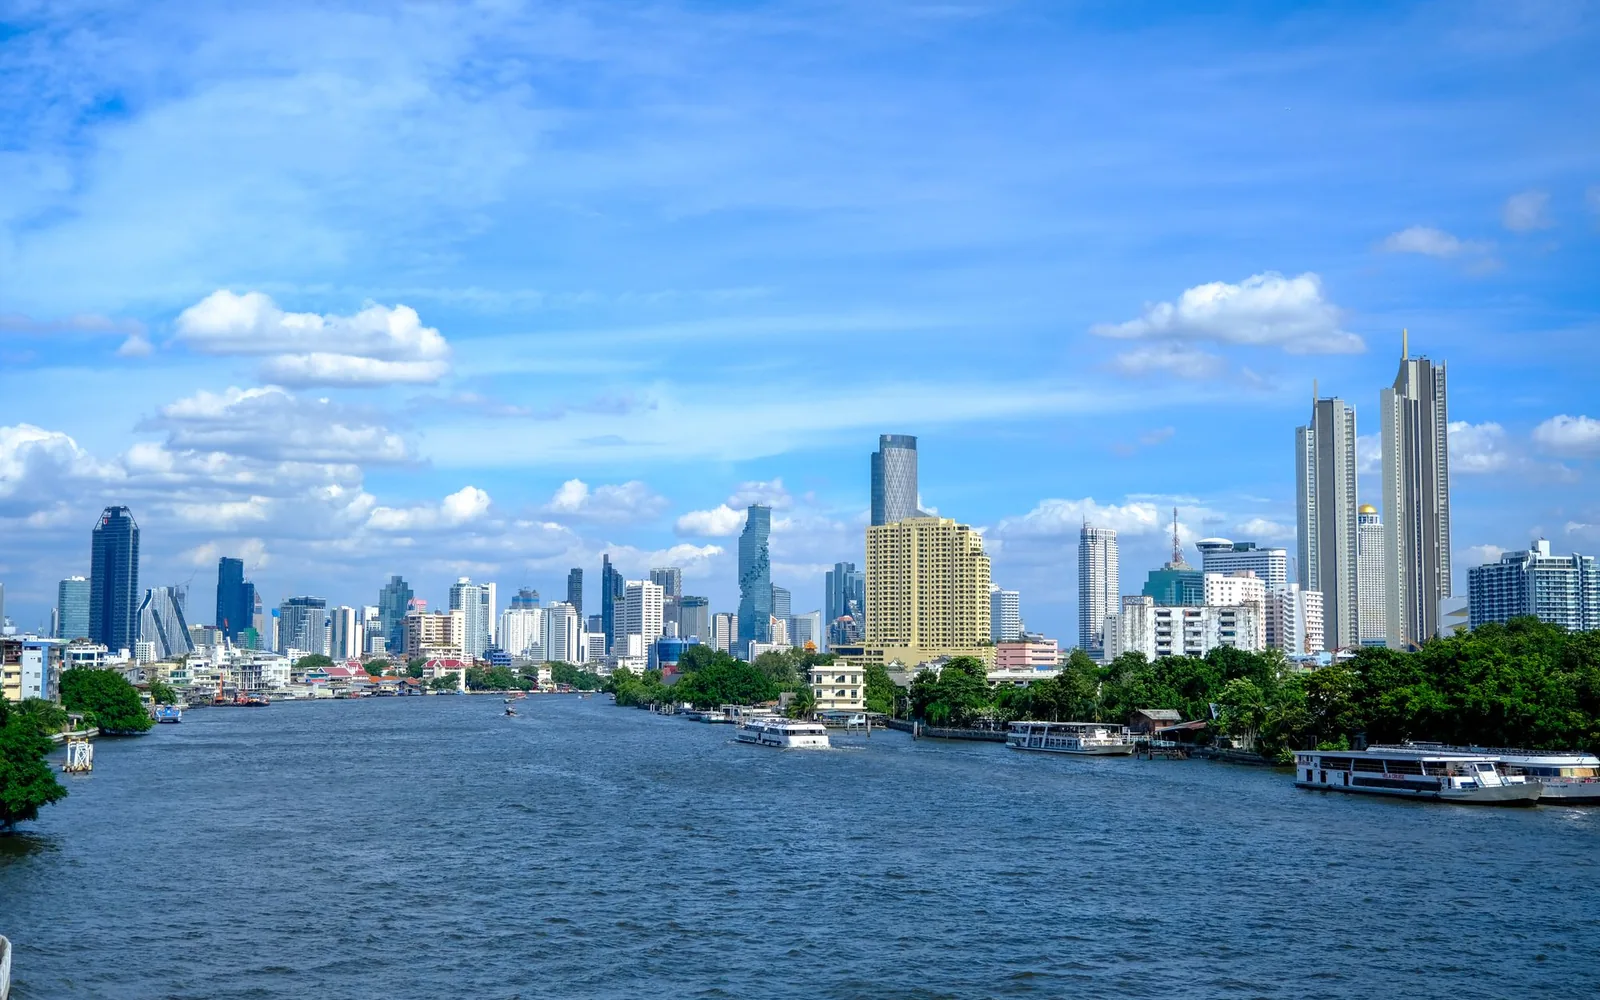
A beach town, Bangkok, Chiang Mai, and Hua Hin can have very different rents, air quality, weather, hospitals, and social pace. Put the exact neighborhood—not just the country—on your shortlist.
Try this: Compare two specific neighborhoods using actual rental listings. Add a transport estimate based on your own likely errands.
3. Healthcare needs a local test
Find the hospitals, insurers, specialists, and medication access near where you would live. A good private hospital in a major city does not automatically solve care in every town.
Try this: Write down your regular care needs and contact a provider before choosing a lease. Keep its address and contact details offline.
4. Plan for the seasons you did not visit
Heat, humidity, rain, smoke, and tourist seasons can change the everyday experience. Visit at a less convenient time of year before signing a long lease.
Try this: Make a calendar of the months you expect to stay. Investigate conditions for those months and plan a trial visit accordingly.
5. Budget for money movement and trips home
A low daily cost can hide exchange-rate swings, banking friction, insurance, flights, and regular travel to see family. Include those in a monthly and annual plan.
Try this: Ask your bank for its fee schedule and compare the total received after fees. Avoid building a budget around one favorable exchange-rate screenshot.
6. Try a normal month before a permanent move
Rent first. Do errands, see a doctor, pay bills, use local transport, and see how the place feels after the novelty fades.
Try this: Spend a few days doing nothing touristy. Buy groceries, do laundry, and try an ordinary journey home after dark. That is useful research.
7. The season can change the answer
Thailand’s heat and rain are not background details. In the north, smoke season can affect outdoor life and air quality; coastal areas have different monsoon patterns; an island route that feels easy in dry weather may be less convenient during storms. Choose trial dates that reveal a difficult season, then check the exact city rather than a national climate chart. Inspect drainage, shade, air-conditioning condition, and indoor air filtration in the home you are considering.
8. Private healthcare still requires a personal plan
A well-regarded hospital is useful only if it provides the care you need, accepts your payment or insurance arrangement, and is reachable from home. Make a one-page care inventory: prescriptions, routine tests, specialists, mobility needs, and emergency contacts. Identify a nearby clinic and a higher-level hospital, then ask an insurer about networks, exclusions, age limits, pre-existing conditions, renewals, and evacuation. Keep written answers and do not infer individual coverage from Thailand’s general medical reputation.
9. Build transport around the neighborhood, not the city name
Bangkok can be rail-connected or taxi-dependent depending on the address. Chiang Mai, Hua Hin, and Phuket create different questions about scooters, cars, ride-hailing, traffic, and evening travel. If you will not ride a scooter, do not use a scooter budget. Price the journeys you would actually make and test them in heat and rain. A less expensive home can cost more overall when every appointment and social visit needs a long car trip.
10. Keep residence administration in its own calendar
Long-stay categories can involve financial evidence, insurance, reporting, renewals, and travel permissions. Build a calendar from current official instructions and mark every document, appointment, recurring date, and contingency. Keep the legal plan separate from the living-cost worksheet so a strong affordability score cannot hide an eligibility gap. Confirm the route with the Thai embassy or consulate responsible for your application before placing funds or buying services around an assumed approval.